Documentation · Central banks · Pro
Rate spread
The Rate spread panel in WatchTower Terminal: rates against a pair. It is on the Pro plan, and it is built on each bank's own decisions, statements and meeting calendar, and exchange-traded short-rate futures read into the probability of each move.
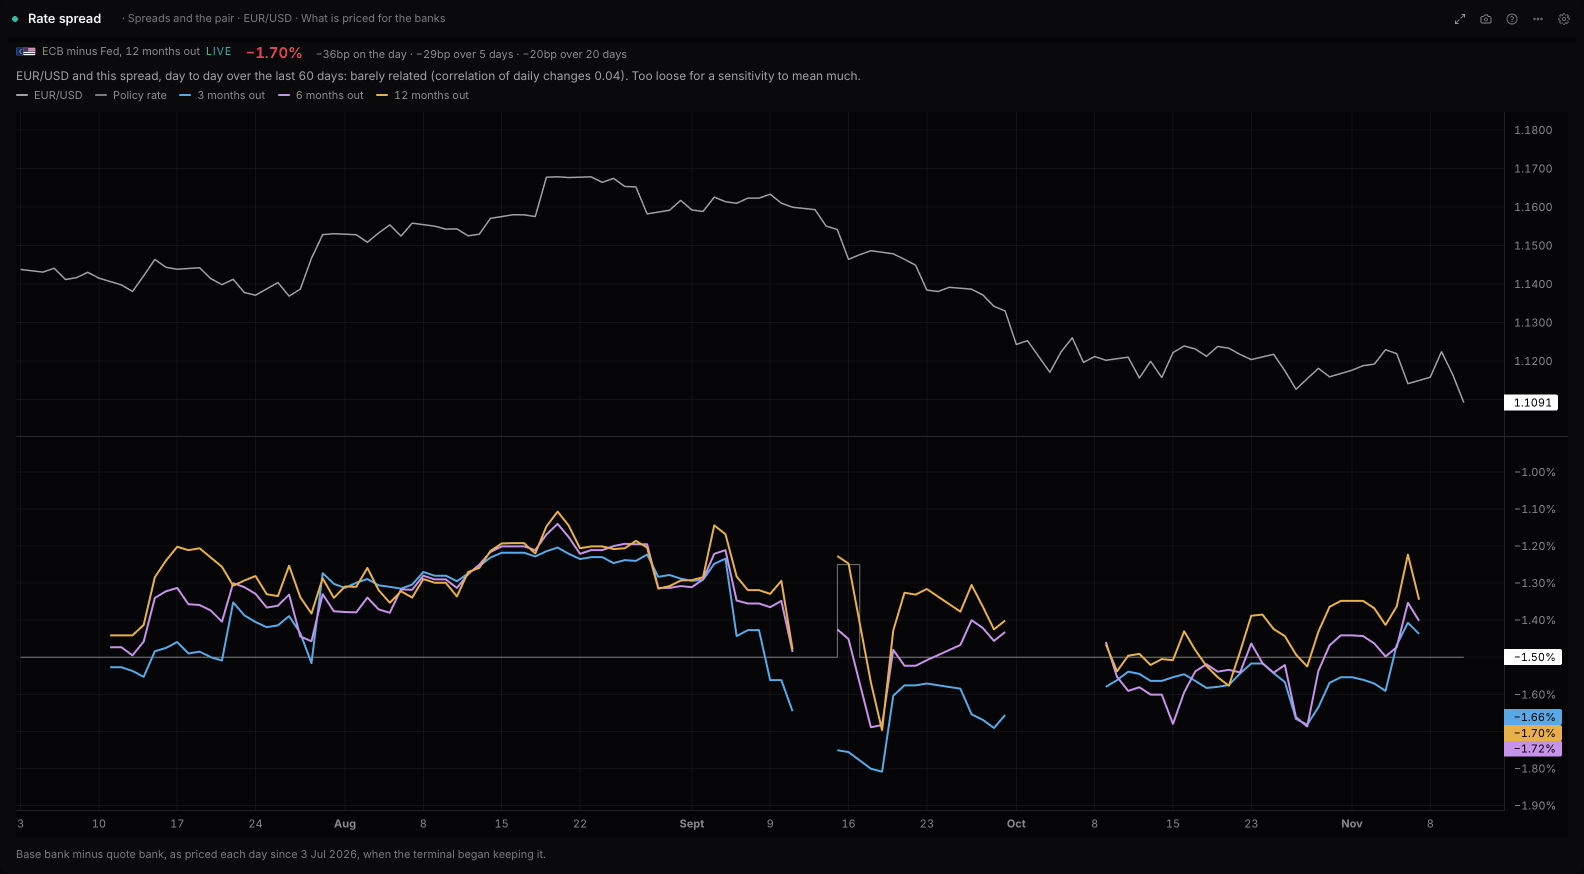
What it shows
Rates against a pair. Its two central banks' priced rates as one spread, at the policy rate and 3, 6 and 12 months out, or its 2-year and 10-year government bond yields, day by day with the pair beside them: the moves over 1, 5 and 20 days, how closely the pair has followed and how far it moves per 10bp. Or the gap at 1, 3, 6, 9 and 12 months out against a week ago, and whether its move is gaining or losing pace. Or the pair's recent move split into the part the rate spreads explain and the part they do not.
Its reads
- Spreads and the pair
- Across horizons
- What moved the pair
The data
- Where it comes from
- Each bank's own decisions, statements and meeting calendar, and exchange-traded short-rate futures read into the probability of each move.
- How often it updates
- Central bank rates and the calendar every 5 minutes.
- In the score
- The central bank input carries 18% of each currency's composite score.
- Plan
- Pro
Settings
| Setting | What it does | Choices |
|---|---|---|
| Read | The spreads drawn day by day against the pair, or the pair’s recent move split into the part the rate spreads explain and the rest. | Spreads and the pair, Across horizons, What moved the pair |
| Pair | The pair’s base currency minus its quote currency. | EUR/GBP, EUR/AUD, EUR/NZD, EUR/USD, EUR/CAD, EUR/CHF, EUR/JPY, GBP/AUD, and 20 more |
| Spreads of | The rates priced for each central bank 3, 6 and 12 months ahead, kept since July 2026; or 2-year and 10-year government bond yields, with years of history. The 2-year follows what is expected of the banks; the 10-year carries growth, inflation and fiscal risk as well. | What is priced for the banks, Government bond yields |
| Spreads drawn | The spread at the policy rate today, and at the rates priced 3, 6 and 12 months ahead. The priced ones move first. | All four, 12 months out, 6 months out, 3 months out, Policy rate |
| Spreads drawn | — | 2-year and 10-year, 2-year, 10-year |
| The move over | The window whose move is split. How much the pair moves for each 10bp of spread is measured on the 120 trading days before it, so the split is never fitted to the move it explains. | The last 20 trading days, The last 60 trading days |
| The pair’s price | — | Show, Hide |
Questions
What does the Rate spread panel show?
Rates against a pair. Its two central banks' priced rates as one spread, at the policy rate and 3, 6 and 12 months out, or its 2-year and 10-year government bond yields, day by day with the pair beside them: the moves over 1, 5 and 20 days, how closely the pair has followed and how far it moves per 10bp. Or the gap at 1, 3, 6, 9 and 12 months out against a week ago, and whether its move is gaining or losing pace. Or the pair's recent move split into the part the rate spreads explain and the part they do not.
Where does Rate spread's data come from, and how often does it update?
Each bank's own decisions, statements and meeting calendar, and exchange-traded short-rate futures read into the probability of each move. Central bank rates and the calendar every 5 minutes.
Is Rate spread free?
Rate spread is on the Pro plan: $10 for the first month, then $49 a month, or $490 a year.
Does Rate spread feed the composite score?
The central bank input carries 18% of each currency's composite score.
Free on this site: Rate differentials explained · The 2027 rate outlook
Also in Central banks: Central bank · Forecast tracker · Next decisions · Rates across banks
WatchTower Terminal has 50 panels; this page documents one. Nothing here is financial advice.